
Do You Have to Disclose Past Flooding When You Sell a Tampa House for Cash?
Yes. Florida law requires a seller of residential property to give the buyer a written flood disclosure at or before the time the sales contract is signed, and the statute does not carve out cash or as-is sales. Sell My House Fast Tampa is a fully insured, experienced local company that buys flood-affected and flood-prone homes across Tampa Bay with its own funds. Meet our experienced local team, see how our process works, read our FAQs, or request a no-obligation cash offer and we will explain what to expect.
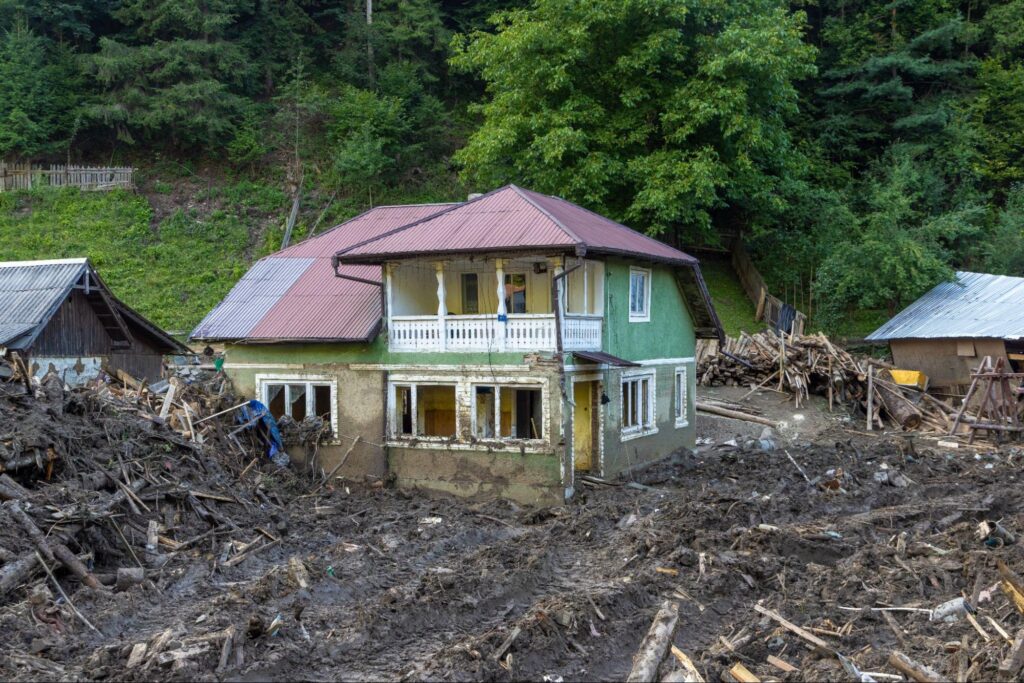
The form asks whether you know of flooding that damaged the property while you owned it, whether you filed a flood-related insurance claim, and whether you received flood-related assistance from any source, such as FEMA. It must reach the buyer before the contract is signed.
What Is the Issue? Florida’s Flood Disclosure Rule
For years, Florida had no statute telling sellers to disclose flooding. Courts relied on a rule from the Florida Supreme Court’s 1985 Johnson v. Davis decision: sellers must share known facts that materially affect a home’s value and are not readily observable. Two recent laws added a specific flood form.
A 2024 law (House Bill 1049) created Section 689.302 of the Florida Statutes, effective October 1, 2024. A 2025 law (Senate Bill 948) expanded it, effective October 1, 2025. Under the current statute, the seller completes a flood disclosure and gives it to the purchaser at or before the time the sales contract is executed. Florida Realtors publishes a standard version of the form (FD-2) that follows the statutory wording.
| Item | What it asks | Plain-English meaning |
| Insurance notice | Homeowners’ policies do not cover flood damage, and the buyer is encouraged to discuss flood insurance with an insurance agent | A standard notice to the buyer; nothing for you to decide |
| Knowledge of flooding | Whether you have knowledge of any flooding that has damaged the property during your ownership | Answer yes if you know flooding damaged the property while you owned it, claim or no claim |
| Insurance claim | Whether you filed a claim with an insurance provider for flood damage, including a National Flood Insurance Program claim | Answer yes if a flood claim was filed on the property |
| Assistance | Whether you received assistance for flood damage to the property, including but not limited to assistance from FEMA | Answer yes if you received flood-related assistance from any source, federal, state, local, or private |
| Definition of flooding | Partial or complete inundation of the property from overflowing inland or tidal waters, unusual and rapid runoff or surface water from an established water source such as a river, stream, or drainage ditch, or sustained standing water from rainfall | Storm surge, creek or canal overflow, ditch overflow, and long-standing rainwater can all count |
Each answer is yes or no, and the form does not ask for details. You can read the exact wording in the enrolled text of Florida’s 2025 flood disclosure law (CS/CS/SB 948), and Florida Realtors summarizes the expanded disclosure for sellers.
Does the Law Apply to Cash and As-Is Sales?
Yes, as far as the statute’s text shows. The duty falls on “a seller” of residential real property, and the law has no exception for cash buyers, investors, or as-is contracts. We did not find one in the enrolled text.
As-is means the buyer accepts the property’s condition. It does not let a seller withhold known material facts. The Florida Senate staff analysis of the 2025 bill notes that the seller’s duty to disclose known facts applies even when the buyer agrees to purchase as-is. See why selling your Tampa home as-is saves time and money, and remember that as-is never replaces the disclosure.
Cash buyers usually inspect the home themselves, but your disclosure duty does not depend on how sophisticated the buyer is. The statute does not spell out a specific penalty for leaving something off, but the Senate staff analysis notes the new requirements may increase the potential for lawsuits and damages when a required disclosure is not made. Accuracy matters.
What Causes the Confusion? Five Common Misunderstandings
| Common belief | What to know |
| Cash or as-is means no disclosure | The statute has no cash or as-is exception, and Florida’s general duty to disclose known material facts applies to as-is sales. |
| No insurance claim means nothing to disclose | Since October 1, 2025, the form asks about any flooding you know damaged the property during your ownership, not only claims. |
| I must disclose my FEMA flood zone | The statutory form does not ask for your flood zone designation, but buyers will check the map, so answer any question about it accurately. |
| Repairs erase the history | The question asks whether flooding damaged the property during your ownership. Completed repairs do not change the answer, but repair records help the buyer understand it. |
| I bought the home after it flooded | The form focuses on flooding during your ownership, but other known material facts may still need to be shared. Ask an attorney how this applies to you. |
Warning Signs You Need to Slow Down and Document
- Water lines, staining, or replaced drywall and flooring from a past event.
- A past homeowners or flood insurance claim, or FEMA assistance letters.
- Standing water after heavy rain, or an overflowing ditch, canal, or retention pond nearby.
- Mold or musty odors that returned after cleanup.
- A lender or insurer that required flood coverage after a storm.
- Neighbors who flooded in the same event.
If water damage or mold is present, see our guides to selling a house with water damage and selling a mold-infested home.
DIY vs. Professional: Who Should Complete the Form?
| You can handle yourself | Get professional help when |
| Gather claim records, repair invoices, photos, and remediation reports | You are unsure whether an event counts as flooding under the statute |
| Look up your flood zone and map history | You inherited the property or are selling for an estate |
| Answer each question based on what you actually know | The home has tenants, or a prior owner’s flood history you only partly know |
| Keep a copy of the signed form | A contract’s disclosure language is unclear or a buyer’s attorney requests changes |
A Florida real estate attorney can confirm how the disclosure applies to you. Your insurance agent can pull claim history, and your city or county building department can confirm permits for storm repairs. Selling an inherited home? Our guide to selling an inherited property for cash explains the process.
Solutions: How to Handle the Disclosure in a Cash Sale
- Gather records: insurance claim history, FEMA or other assistance letters, repair invoices, photos, and any remediation or drying reports.
- Review the statutory form or the Florida Realtors version and answer each question based on what you know. If you are unsure, say what you know and ask an attorney.
- Give the completed form to the buyer at or before the time the contract is signed, not at closing.
- Keep a signed copy and make sure the title company has the full contract package.
- Close out open permits if you can, or tell the buyer about them so the offer reflects them. See selling a home with open permits.
- Compare offers. Flood history affects listings and cash offers, but a cash buyer buys as-is without waiting on a lender or insurer. Our guide to selling after a hurricane or tropical storm covers the next steps.
Cash Buyer vs. Listing When There Is a Flood History
| Factor | Cash buyer | Traditional listing |
| Disclosure form | Required before the contract | Required before the contract |
| Lender and insurer approval | Not needed | Needed for most buyers |
| Repairs | None required; condition is priced in | Often requested after inspection |
| Timeline | 7 to 14 days in most cases | Often 60 to 90 days or more |
| Buyer inspection | Yes, by the buyer | Yes, plus lender and insurance inspections |
Local Context: Flood History Across Tampa Bay
Tampa Bay’s low-lying coast means flood history is common. In Pinellas, Hurricanes Idalia, Helene, and Milton brought surge and rainfall flooding to neighborhoods from the beaches to inland retention-pond communities, and the City of Gulfport reports that more than 600 properties were affected by the 2024 flooding. Hillsborough and Pasco counties also have canal, creek, and drainage-ditch flooding.
Check any address on the FEMA Flood Map Service Center. If a storm damaged your home, Pinellas County’s substantial damage guidance shows which city office to contact for permits and damage determinations.
We buy flood-affected homes in communities such as Gulfport, Hudson, Palmetto, and Oldsmar. For the county-level picture, read our guide to selling a Pinellas County house with flood and insurance problems.
Wondering who will actually buy a flood-affected home? See who buys houses for cash in Tampa for the five buyer types and how to vet each one.
Frequently Asked Questions About Florida’s Flood Disclosure Law
Do I have to disclose past flooding when I sell my Florida house?
Generally yes. Section 689.302 of the Florida Statutes requires a seller of residential property to complete a flood disclosure and give it to the buyer at or before the time the sales contract is signed. Ask an attorney how it applies to your situation.
Does the flood disclosure apply if I sell for cash?
The statute applies to a seller of residential real property and, as written, has no exception for cash sales. A cash buyer may inspect the home on their own, but your duty to complete the form does not depend on how the buyer pays.
Does selling as-is remove the flood disclosure requirement?
No. As-is means the buyer accepts the property’s condition. Florida’s duty to disclose known material facts still applies to as-is sales, and the flood disclosure form is a separate statutory requirement.
What does the Florida flood disclosure form ask?
It includes a flood insurance notice and asks whether you know of flooding that damaged the property during your ownership, whether you filed a flood-related insurance claim, and whether you received assistance for flood damage from any source, such as FEMA.
Do I have to disclose flooding if I never filed an insurance claim?
Since October 1, 2025, the form asks whether you know of flooding that damaged the property during your ownership, whether or not you filed a claim. If you know about it, the answer is yes.
When do I have to give the buyer the flood disclosure?
At or before the time the sales contract is signed. Waiting until closing does not meet the statute’s timing, so prepare the form before you sign with any buyer.
What counts as flooding under the law?
The statute defines flooding as partial or complete inundation of the property from overflowing inland or tidal waters, unusual and rapid runoff or surface water from an established water source such as a river, stream, or drainage ditch, or sustained standing water from rainfall.
Do I have to say whether my home is in a FEMA flood zone?
The statutory form does not ask for your flood zone designation. Buyers can check the FEMA map themselves, so answer any direct question about it accurately and consider sharing the zone upfront.
What if I bought the house after it flooded?
The form focuses on flooding during your ownership. Other known facts that materially affect value may still need to be shared under Florida’s general disclosure duty, so ask an attorney how that applies to your situation.
I inherited a house that flooded. What do I disclose?
Disclose what you know about flooding, claims, and assistance, and speak with the estate’s attorney about the ownership period the form covers. We work with heirs and attorneys and buy inherited homes as they stand.
What happens if I leave something off the form?
The statute does not state a specific penalty, but the Senate staff analysis notes the requirements may increase the potential for lawsuits and damages when a required disclosure is not made. Complete the form accurately and keep records.
Does repaired flood damage still need to be disclosed?
Repairs do not erase the history. The form asks whether flooding damaged the property during your ownership, so repaired damage still counts. Repair invoices, permits, and photos help the buyer understand what happened.
Does the 2025 law affect landlords, condos, or mobile home parks?
Yes. The 2025 law added flood disclosures for landlords on leases of one year or longer, condominium developers, and mobile home park owners. When an owner resells a condominium unit, the general seller form in Section 689.302 applies.
Will a flood history lower what a cash buyer offers?
Flood history, repairs, and insurability are part of how any buyer evaluates a home, so they can influence the offer. We buy as-is and explain our reasoning in writing so you can compare it with a listing.
How do I get a cash offer for a flood-affected house?
Call 813-945-6701 or request an offer online. We schedule a short walkthrough and send a written, no-obligation offer within 24 hours. Have your insurance claim records and repair invoices ready if you have them.
When to Call Sell My House Fast Tampa
If a flood, a repair, or an insurance claim is part of your home’s story, Sell My House Fast Tampa can buy it as-is without a lender or insurer in the way. We are a fully insured, experienced local company that buys with its own funds, and you still complete the flood disclosure honestly before the contract is signed.
| What We Offer | What It Means for You |
| Fully insured, experienced local cash buying team | Meet the people behind every offer on our About Us. We buy across Hillsborough, Pinellas, Pasco, Manatee, and Hernando counties. |
| Written cash offer within 24 hours of walkthrough | Every step, from first call to closing, is laid out on our How It Works. |
| Zero repairs required | Flood damage, mold, water-stained walls, and deferred repairs never hold up our purchase. See how we handle homes in any condition. |
| No commissions or seller closing costs | The offer is what you keep after mortgage payoff. Questions? Our FAQs answer the common ones. |
| Close in 7 to 14 days or on your timeline | You choose the date. See the day-by-day cash sale timeline. |
| We buy homes with a flood history | Flood damage, repairs, and insurance history are evaluated as part of the offer, and we buy as-is. |
| No obligation to accept | Requesting an offer costs nothing. Request your offer or call 813-945-6701. |
Ready to Sell Your Flood-Affected Tampa Bay Home?
Tell us about your home and its history. We will schedule a short walkthrough and send a written offer within 24 hours, with no repairs, no commissions, and no obligation.
Written cash offer within 24 hours. Close in as few as 7 days. No repairs, no commissions, no seller-side fees.
Call 813-945-6701 or fill out our online form. Prefer to read first? See how our process works or browse our frequently asked questions. Sell My House Fast Tampa is fully insured and experienced throughout Tampa Bay.